BRAC Bank passes $2.5 billion in remittance inflows in nine months
Bdbusinessdaily.com – BRAC Bank has received more than $2.5 billion in foreign remittances during the first nine months of 2026, exceeding the $2.2 billion it collected across all of 2025. The result places the bank ahead of its previous annual high with three months still remaining in the year.
The lender is now aiming to bring total remittance inflows above $3 billion by the end of 2026. That target follows five straight years of growth in its remittance business and reflects the expanding role of formal banking channels for Bangladeshis living and working overseas.
International connections and digital transfer systems
Foreign remittances are a vital source of financial support for many Bangladeshi households. For families receiving money from abroad, the speed, safety and availability of a transfer can have a direct impact on everyday expenses, savings plans and longer-term financial decisions.
BRAC Bank links customers with exchange-house partners in key overseas remittance markets. Its network covers major corridors in the Middle East, Southeast Asia, Europe, North America and the wider Asia-Pacific region, allowing expatriate Bangladeshis to send funds home through established formal channels.
The bank has strengthened its international transfer process through host-to-host connections and application programming interface, or API, integration with overseas partners. These systems are intended to make cross-border transactions quicker, more dependable and more secure for senders and recipients.
Technology has become increasingly important in remittance services because it can reduce friction between the point where money is sent abroad and the point where it reaches a beneficiary in Bangladesh. Reliable connectivity also helps banks and exchange-house partners process transfers efficiently while maintaining the safeguards expected in formal financial services.
Access for recipients across Bangladesh
Once remittances arrive in Bangladesh, recipients can use BRAC Bank’s branch, sub-branch and agent-banking network. The reach of these outlets is especially relevant for families outside larger cities, where convenient access to banking services can determine whether funds are received through formal channels.
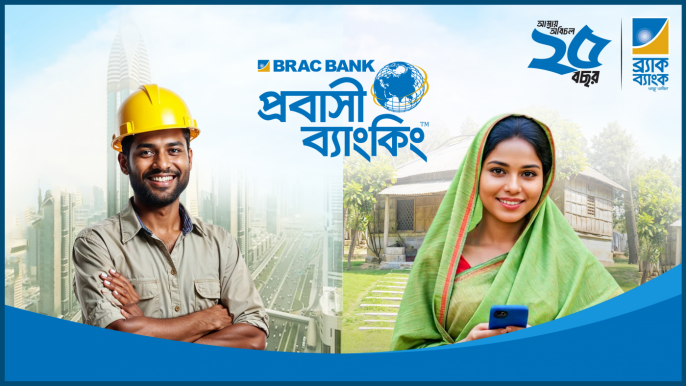
The bank’s approach extends beyond the transfer itself. It has developed products intended for non-resident Bangladeshis, commonly known as NRBs, as well as for their family members at home. These include the Probashi Virtual Savings Account, Probashi Poribar Account, TARA Probashi Poribar Account and services provided through its offshore banking unit.
Eligible NRBs can open accounts from overseas through electronic know-your-customer verification. They can then use the Astha app to manage banking needs while living outside Bangladesh. Available facilities include money transfers, bill payments, deposit management and deposit pension scheme services.
For expatriates, these options can help preserve an active banking relationship in Bangladesh without requiring regular in-person visits. For families, the services offer a way to handle incoming funds, household payments and savings through the banking system. The wider objective is to support the use of remittance income not only for immediate needs, but also for longer-term financial security.
Community engagement around formal remittance use
BRAC Bank also conducts “Uthan Boithak”, or courtyard meetings, with remittance-receiving communities. These sessions are designed to make families more aware of formal channels for receiving money and of the banking products available to them.
Such local engagement matters because a remittance transfer often involves more than the person sending it. Recipients may need to decide how to receive, spend, save or invest the funds. Clearer familiarity with banking options can help households make use of services that fit their circumstances.
The bank’s latest performance suggests that its combination of international partnerships, digital systems and domestic access points is gaining traction among overseas Bangladeshis and their beneficiaries. Its goal of crossing $3 billion in annual remittance inflows would represent another step forward if the pace is maintained through the final quarter.
“Crossing $2.5 billion in remittance inflows within three quarters of the year reflects the trust placed in us by expatriate Bangladeshis and our international partners. Our plan is to provide value-added services with tailor-made products for wage earners so that they can invest their money efficiently in Bangladesh for long-term financial security.”
Managing Director and CEO Tareq Refat Ullah Khan said the milestone reflects confidence from both expatriate Bangladeshis and the bank’s international partners. He highlighted the importance of providing products designed for wage earners who want to use their money productively in Bangladesh.
“We will continue investing in technology, human capital and international strategic alliances to make remittances faster, safer and more convenient for expatriates and their families.”
With its remittance volume already above last year’s full-year total, BRAC Bank is positioning its overseas banking services around convenience, access and financial planning. Its progress during 2026 illustrates how international relationships, digital account tools and local service networks can work together to support expatriate Bangladeshis and the families who depend on their transfers.
Related Reading
Frequently Asked Questions
What is BRAC Bank s foreign remittances cross 2?
BRAC Bank s foreign remittances cross 2 is the main topic of this guide. The article explains the context, practical details, and next steps readers should understand.
Why does BRAC Bank s foreign remittances cross 2 matter?
BRAC Bank s foreign remittances cross 2 matters because readers are looking for a useful answer, not just a short summary. Good content should match search intent and help them decide what to do next.